文
A
On August 26, Qifu Technology (NASDAQ: QFIN) released its unaudited financial results for the second quarter and first half of 2026.
Overall, this remains a report marked by ongoing adjustment. Revenue and profit continued to come under pressure, but risk indicators have shown marginal improvement. Against the backdrop of China's credit-technology industry, platforms are generally recalibrating the pace of growth.
For Qifu Technology, the more important Q2 questions concern not only fluctuations in reported results, but also whether risk repair can continue and whether its light-capital business, ICE, and overseas operations can gradually take over as new growth drivers.
I. Core Performance: Revenue Continues to Decline, but the Financial Base Has Not Deteriorated in Tandem
In Q2 2026, Qifu Technology's total net revenue was RMB 3.57 billion, down 31.6% year on year. Net income was RMB 400 million, down 76.8% year on year, and net margin fell to 11.3%. Looking across consecutive quarters, these indicators are also clearly in a downtrend.
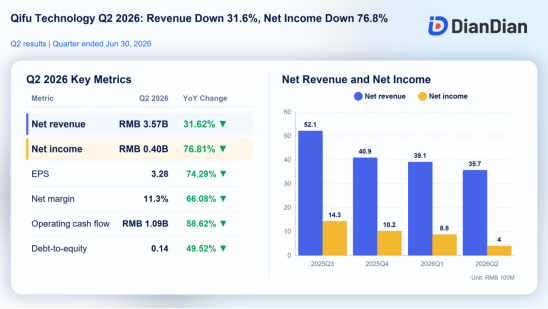
Diandian's analysis suggests that the consecutive decline in revenue indicates that the company remains in a period of business adjustment and that the impact of scale contraction on its revenue base has not yet fully cleared. The profit side has also been affected by additional factors, so market attention to the pace of earnings recovery is expected to increase further.
However, pressure on earnings does not mean that the financial base has deteriorated in tandem. Qifu Technology's operating cash flow was RMB 1.09 billion in Q2, while its debt-to-equity ratio fell to 0.14. Short-term liquidity and the balance sheet have retained a degree of resilience.
In Q2 2026, Qifu Technology generated RMB 2.60 billion from credit-driven services, accounting for 72.8% of total revenue and remaining the largest component. Platform services contributed RMB 970 million, or 27.2%.
By revenue item, financing revenue was RMB 1.84 billion, accounting for 51.5% of total net revenue and remaining the largest source. Revenue from the release of guarantee liabilities was RMB 660 million, or 18.5%. Referral service fees, namely referral and traffic-acquisition revenue related to the ICE platform, amounted to RMB 370 million, or 10.4%.
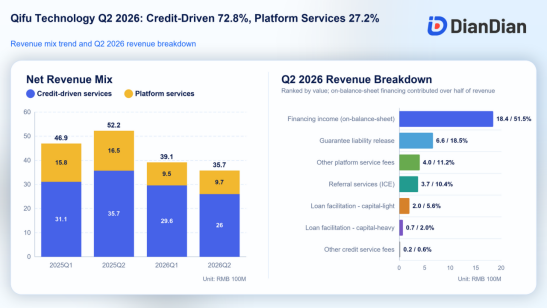
This change should not, however, be simply interpreted as an enhancement of platform capabilities. The absolute scale of platform-service revenue has not expanded materially; its share has risen structurally mainly because credit-driven services contracted faster.
In other words, Qifu Technology has a clear light-capital direction, but it is not yet able to offset the impact of the decline in its core business.
III. Operating Quality: Expense Ratios Improve, While Risk Provisions Remain the Biggest Pressure Point
In Q2 2026, Qifu Technology's operating costs and expenses totaled RMB 2.41 billion, representing approximately 67.4% of total net revenue, down 7.5 percentage points from Q1 2026.
By category, risk provisions and guarantee-related items amounted to RMB 1.07 billion, accounting for 44.4% of operating costs and expenses. Origination and servicing expenses, including loan facilitation, post-loan services, and collections, totaled RMB 680 million, or 28.2%. Sales and marketing expenses were RMB 400 million, or 16.6%.
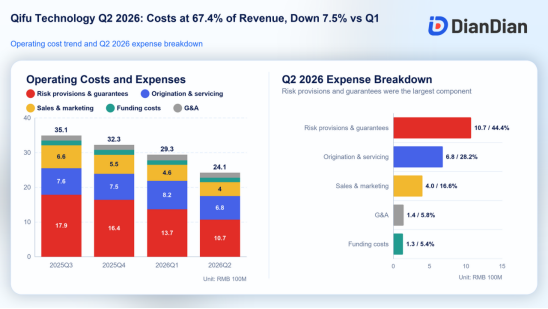
Improvement on Qifu Technology's expense side is relatively clear. Operating costs and expenses fell from RMB 3.51 billion in Q3 2025 to RMB 2.41 billion in Q2 2026, showing that the company has made progress in cost control and risk-exposure management.
Sales and marketing expenses fell to RMB 400 million, which is not particularly high even compared with peers that are actively expanding overseas. Going forward, the more important question is not how much total marketing expense declines, but whether spending resources are being tilted further toward overseas channels, branding, and localized operations.
Earnings recovery must be assessed from both the operating and net-income perspectives. The former depends on whether risk provisions can decline as asset quality improves; the latter also requires observation of whether the margin can return to a relatively normal level after the one-off tax impact in Q2 fades.
IV. Risk and Scale: Marginal Risk Repair Is Underway, but Stabilization of Loan Scale Remains Unconfirmed
Qifu Technology's risk indicators improved in Q2. The delinquency rate for loans overdue by more than 90 days fell from 3.50% in Q1 2026 to 2.83% in Q2 2026. The Day-1 delinquency rate edged down from 5.7% to 5.6%, while the 30-day collection rate rose to 88.1%.
The scale of the business, however, has not yet stopped declining. Loan originations fell from RMB 83.28 billion in Q3 2025 to RMB 63.38 billion in Q2 2026, while the outstanding loan balance declined from RMB 138.11 billion to RMB 107.56 billion. Over the same period, the structural shift toward light-capital operations, ICE, and technology solutions continued.
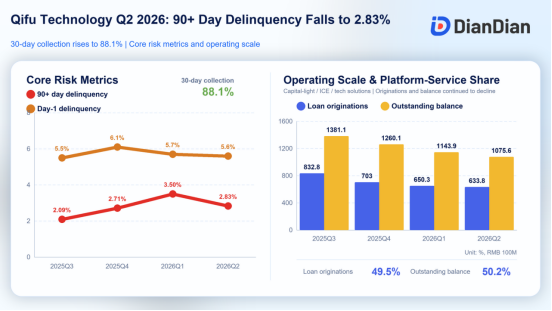
Diandian's analysis considers the improvement in risk indicators a relatively positive Q2 signal. It suggests that the company's earlier structural adjustments and risk-control optimization are beginning to take effect, with the business focus shifting toward rebalancing risk and returns.
The key issue going forward is not whether the delinquency rate declines in a single quarter, but whether improving risk conditions can support stabilization in loan scale. If asset quality continues to recover and the declines in loan originations and outstanding loan balance gradually narrow, Qifu Technology's revenue and profit elasticity will have a clearer foundation for recovery.
Qifu Technology showed signs of risk repair in Q2, but the sustainability of this improvement still needs to be evaluated through subsequent data. Revenue and business scale have not yet stabilized, and a growth turnaround will take time.
In an industry environment focused on controlling scale, lowering interest rates, and strengthening risk controls, the room for imagination in domestic credit operations has narrowed significantly. For the company, domestic operations are better suited to serving as a foundation for cash flow and asset quality, rather than the primary source of incremental growth.
Management also remains cautious about future growth. In the Q2 announcement, CEO Wu Haisheng said that industry adjustment is expected to continue and that the company will take a more prudent approach to growth, risk, and capital allocation. At the same time, the company is 'pursuing overseas expansion in a disciplined manner' and calibrating risk and capital deployment to ensure attractive returns.
Diandian's analysis suggests that the key future variables for Qifu Technology lie in the pace at which its overseas markets and platform services deliver results. Europe, Latin America, and other markets remain at an early stage and will make limited short-term contributions. If the company can accelerate the development of local customer acquisition, risk pricing, and operating capabilities, however, overseas operations could become a new growth pillar.
The next key question is whether overseas operations and platform services can take over as growth drivers. First, overseas investment must increase and begin to generate revenue that can be disclosed. Second, ICE, referral and traffic-acquisition services, and technology services must provide a more stable source of revenue that is less capital intensive.
Before these signals emerge, Qifu Technology remains in the risk-repair phase, and a genuine growth turnaround may still be some distance away.
Appendix: Representative Regional Developments and Growth Trends
Qifu Technology's overseas footprint already covers the United Kingdom and Latin America, while it continues to seek entry points in Southeast Asia. From the perspective of regional penetration, the key to going overseas is not simply entering more markets, but establishing a stable position in priority markets.
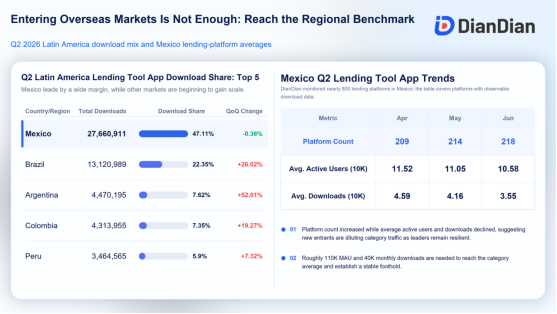
Mexico in Latin America provides an example: the number of platforms is increasing, but average activity and downloads are declining in tandem, suggesting that traffic is still being diverted and that an opportunity window remains open.
For credit-technology companies, overseas operations may only be considered truly established after first crossing the regional benchmark line and then moving closer to the leading group.