文
A
Downloads and Revenue Both Grow as Google Play's Monetization Efficiency Gradually Improves
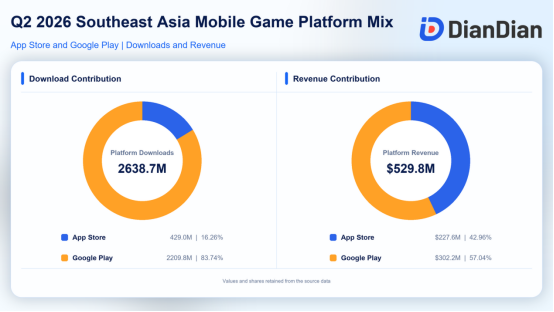
According to Diandian, total mobile game downloads and revenue in Southeast Asia increased by 3.22% and 4.34% quarter on quarter, respectively, in the second quarter of 2026. Growth in both metrics was likewise driven by mid-tier markets. Singapore recorded particularly strong gains in both downloads and revenue; its share of regional revenue surpassed those of Indonesia and Malaysia to rank second, behind only Thailand. Cambodia also performed strongly on the revenue side, posting quarter-on-quarter growth of more than 22.6%. Compared with the same period in 2025, Southeast Asia also saw notable year-on-year growth in both mobile game downloads and revenue, with downloads rising by nearly double digits, at 9.68%. This suggests that the region's traffic dividend is still being unlocked and that the market retains room for further expansion.
By platform, Google Play accounted for the larger share of both downloads and revenue. Its share of downloads exceeded 80%, making it the primary source of traffic behind the expansion of Southeast Asia's mobile game market. The App Store, despite contributing only 16.26% of downloads, generated 42.96% of revenue, reflecting its role in converting higher-value users into payers. Its revenue per download was approximately 3.9 times that of Google Play. Over the past year, however, Google Play's share of downloads has gradually declined amid overall market growth, while its revenue share has increased significantly, indicating continued improvement in monetization efficiency per download.
By genre, casual, simulation, and action games ranked as the three largest categories by downloads, while strategy, role-playing, and casual games led by revenue. Puzzle games posted clear growth in both downloads and revenue, while casual games recorded even stronger revenue growth, making the category an important contributor to overall market revenue expansion.
Light Casual Games Flourish Across Multiple Subgenres as Low-Barrier Products Rapidly Acquire Users
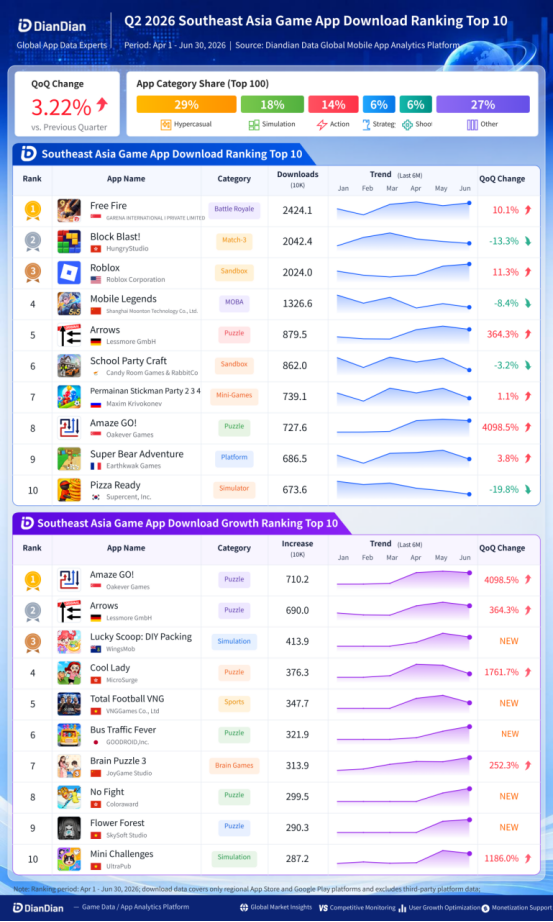
During the period, two arrow-based puzzle games, Arrows and Amaze GO!, delivered standout performances in Southeast Asia. Amaze GO! generated more than 7.27 million downloads, up approximately 4,098.53% quarter on quarter, while Arrows recorded more than 8.79 million downloads in Q2, an increase of approximately 364.28%. The two titles ranked first and second, respectively, on the regional list of fastest-rising mobile games by downloads. Several other light casual titles built around familiar gameplay, including Cool Lady, Bus Traffic Fever, and Mini Challenges, also performed strongly in Q2 and collectively dominated the download rankings.
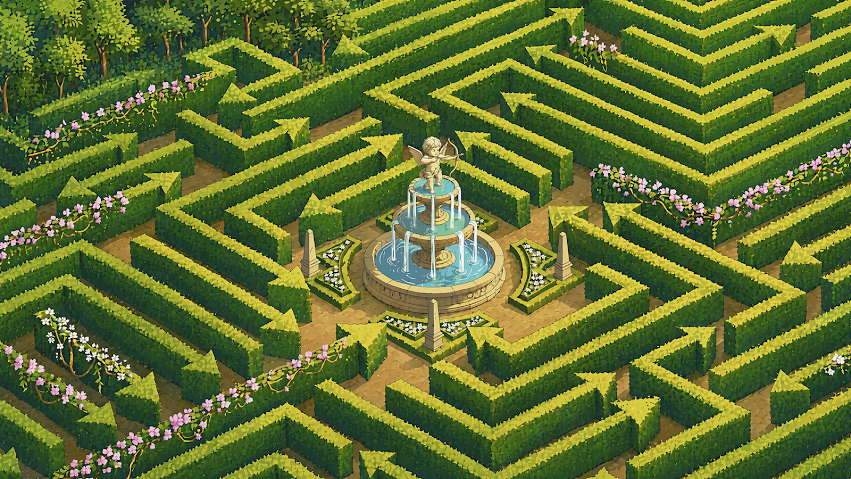
The concentrated growth of multiple puzzle titles shows that not all new traffic in Southeast Asia is flowing to midcore and hardcore games. Light casual and puzzle categories still have substantial room for user acquisition. Casual gameplay featuring simple rules, lightweight controls, short and fast-paced levels, and a mix of stress relief and cognitive challenge is becoming an important destination for new regional traffic. On the one hand, low barriers to entry and limited reliance on text help products bridge linguistic and cultural differences and adapt to Southeast Asia's multi-country, multi-tier user base. On the other hand, mechanics such as arrow puzzles can be demonstrated intuitively through short-form video creatives, reducing both advertising communication costs and the effort required for users to understand the game.
As more developers enter the market, however, simple gameplay and paid user acquisition alone are no longer sufficient to create a lasting advantage. In future competition among casual games, the frequency of level updates, difficulty curves, ad load management, feedback after failure, thematic presentation, and localized creatives will all affect retention and monetization. The growth of Arrows and Amaze GO! indicates that distinctive subgenres combining strong visual identity, simple controls, and sustained room for problem-solving are becoming an important way for casual games to capture incremental traffic in the region.
Regional Publishing Strength and Football's Popularity Combine to Propel VNG's New Title
During the period, Total Football VNG, a new football game published by VNG, generated more than 3.47 million downloads in Southeast Asia in its launch quarter, debuting at No. 5 on the Q2 ranking of fastest-rising mobile games. Developed by GALA Sports, the title emphasizes a football experience that is 'Fast, Fun, Fair.' Its ability to attract substantial attention within a short period was supported not only by the tournament buzz surrounding the quadrennial FIFA World Cup, but, more importantly, by VNGGames' accumulated experience in local publishing and operations across Vietnam and the broader Southeast Asian market.
Drawing on VNG's extensive resources in Southeast Asia, Total Football VNG did not rely solely on broad entertainment advertising. Instead, its marketing strategy connected the game with real-world football events, regional players, and esports activities. In Vietnam, VNGGames appointed national-team player Nguyen Dinh Bac as a brand ambassador and featured him in the game's 'Pride of SEA' season card. The publisher subsequently introduced regional players and localized content for markets including Indonesia and Thailand, strengthening the title's connection with local football cultures. The game's inclusion as a competitive title in the inaugural SEA Esports Nations Cup also helped it expand beyond a conventional sports mobile game into esports and event-based settings, enhancing both its competitive appeal and its value for community-driven distribution.
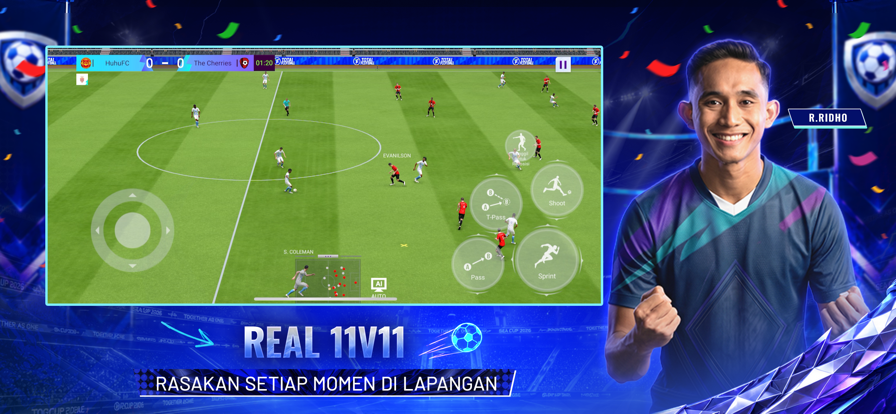
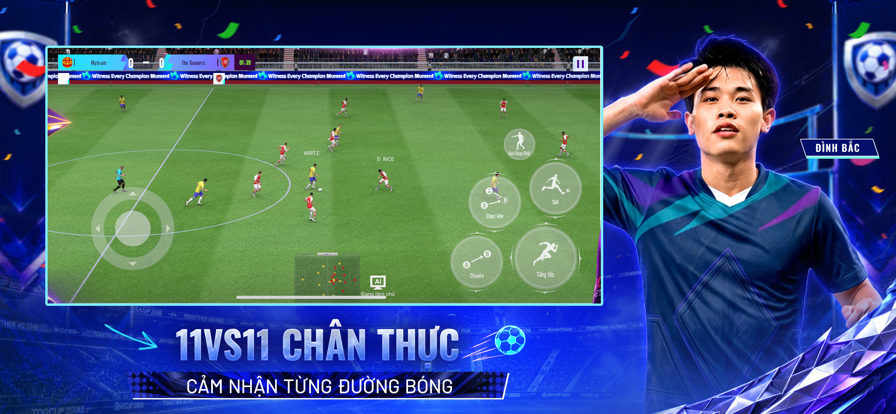
The product pages feature footballers from each respective country as regional ambassadors.
The game itself strengthens the realism and competitiveness of mobile football through officially licensed players, 3D graphics, a VAR system, career mode, ranked matches, tournaments, and other content. According to publicly released information, it holds FIFPro image rights for more than 60,000 players, while the company reported over 3 million pre-registrations in Southeast Asia. In terms of gameplay, Total Football VNG does not rely solely on automated, stat-based matches; it emphasizes player skill in passing, shooting, defending, and controlling the tempo of play. It also features local footballers and region-specific content for Southeast Asia, further enhancing regional users' sense of participation and identification with the game.
From a market perspective, football has a broad mass following in Southeast Asia, and several countries in the region have highly active football and esports communities. Drawing on its deep understanding of the market, VNGGames combined global football content with Southeast Asian local identity through authentic player licensing, regional player cards, and localized goal celebrations. These design choices helped stimulate participation and sharing, laying the foundation for the game's strong start.
Chinese Games Deliver Strong Results, While Midcore and Hardcore Titles Remain the Main Revenue Drivers
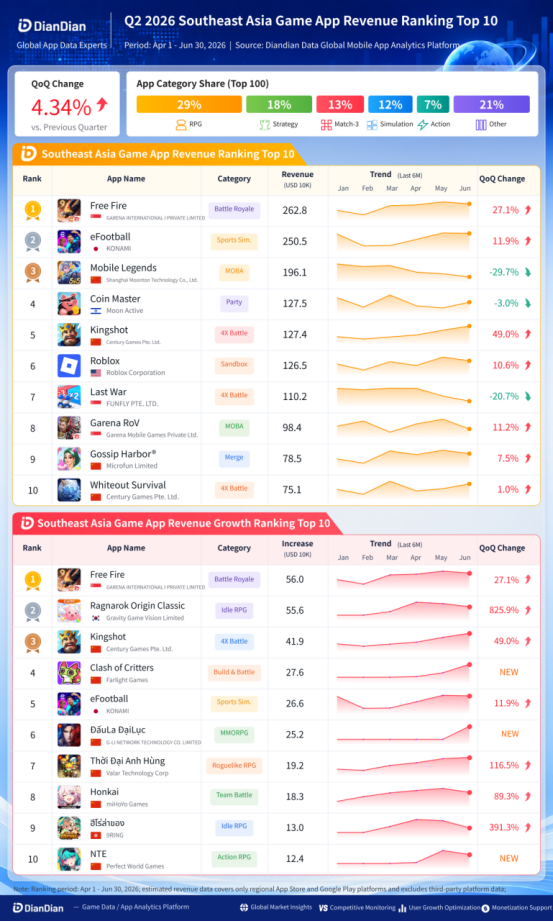
The Q2 revenue rankings show that Chinese-developed games continue to demonstrate strong monetization capabilities in Southeast Asia. Century Games' Kingshot generated estimated regional revenue of more than US$12.74 million in Q2, up 48.97% quarter on quarter and placing it among the top five games by revenue. Another SLG title from the company, Whiteout Survival, also remained firmly in the rankings. Among newer releases, Clash of Critters, Đấu La Đại Lục (Soul Land), and NTE also performed strongly and entered the list of fastest-rising games by revenue, highlighting both the market fit and revenue-capturing capabilities of Chinese games in Southeast Asia.
By genre, midcore and hardcore categories such as strategy and role-playing accounted for the largest shares of revenue. This indicates that Southeast Asian users continue to have stable and clearly defined demand for deeper gaming experiences. Products built around 4X strategy, character development, and team-based combat can extend user lifecycles through city building, resource competition, character progression, alliance cooperation, seasonal events, and similar systems. Continuous updates and time-limited events also encourage repeat spending, making these midcore and hardcore products an important source of market revenue.
The revenue growth of titles such as Kingshot also demonstrates that the competitiveness of Chinese games in Southeast Asia is not based solely on early-stage paid user acquisition. As Southeast Asia has long served as the first stop for Chinese games expanding overseas, years of practice have enabled Chinese developers to build relatively mature capabilities in product development, advertising, localized publishing, and sophisticated live operations.
Even Stronger Growth Across Downloads and Revenue, With Downloads Up More Than 18.5% Year on Year
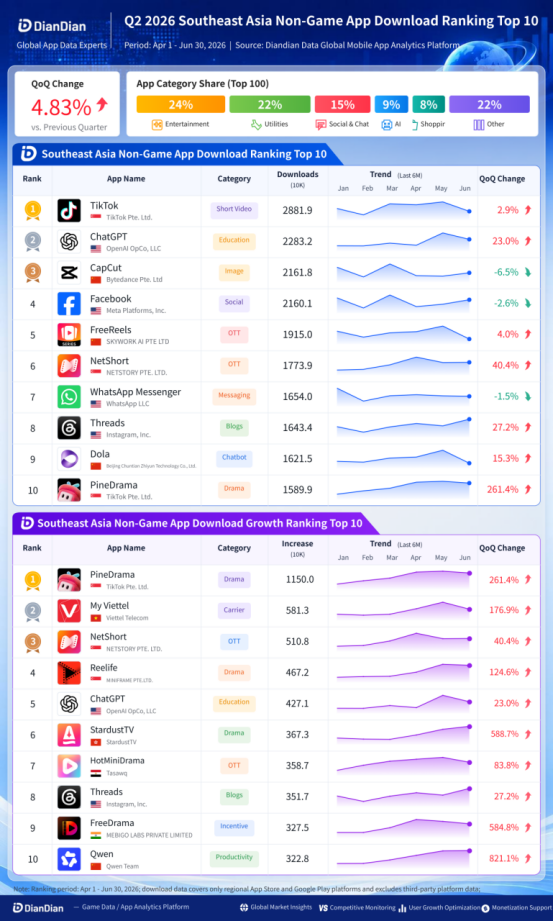
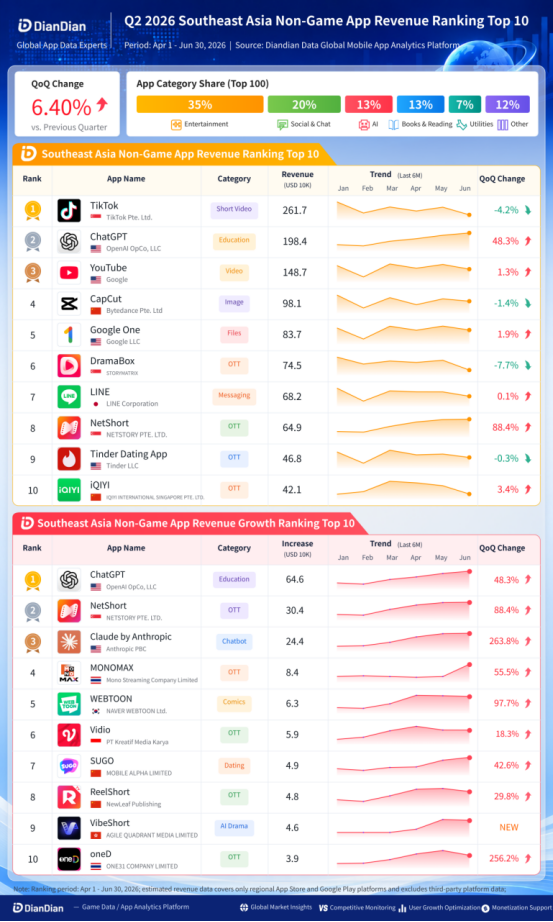
The non-game app market performed even more strongly than mobile games. In the second quarter of 2026, total downloads and revenue for mobile apps in Southeast Asia increased by 4.83% and 6.40% quarter on quarter, respectively. Singapore stood out in both non-game app downloads and revenue, with growth in each metric approaching double digits. Supported by Singapore's performance, mid-tier markets such as Malaysia and Vietnam also expanded rapidly, together becoming the main drivers of the region's overall Q2 growth. On a year-on-year basis, non-game app downloads grew by more than 18.5%, confirming that Southeast Asia's mobile internet market remains in a phase of continued expansion.
By platform, Google Play's broader device coverage and user base in Southeast Asia enabled it to contribute more than 65.6% of non-game app downloads in Q2. The App Store, by contrast, generated more than half of revenue from roughly one-third of downloads. Its relative monetization efficiency per download was approximately 2.3 times that of Google Play, reflecting stronger user spending power and commercialization efficiency. Over the past year, changes in the platforms' contribution shares have broadly mirrored those seen in mobile games, with the monetization-efficiency gap between the two platforms gradually narrowing.
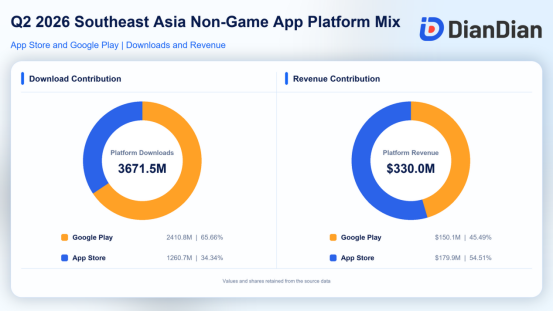
By category, tools, entertainment, and social networking and communications ranked as the three largest categories by downloads, while entertainment, photo and video, and social networking and communications led by revenue. Amid the rapid development of AI technology, tools and productivity apps, which are most closely associated with AI, recorded the strongest growth in both downloads and revenue.
Mandatory Real-Name Verification Triggers a Surge in My Viettel Downloads
During the period, My Viettel, an app operated by Vietnamese telecommunications carrier Viettel, saw downloads increase by more than 176.9% quarter on quarter in Q2. With an increase of over 5.81 million downloads, it rose to No. 2 on Southeast Asia's ranking of fastest-growing non-game apps by downloads. As the operator's official platform for mobile top-ups, plan subscriptions, account management, and telecommunications services, such a sharp fluctuation in downloads is unusual. The app's rapid Q2 growth may have been linked to Vietnam's concentrated rollout of real-name information verification requirements for mobile subscribers.
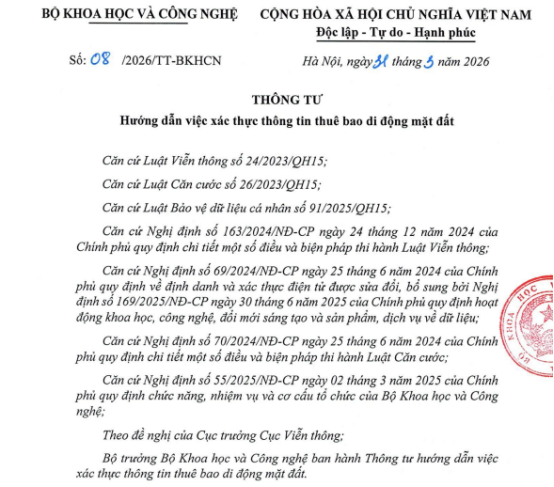
Under Vietnam's Circular No. 08/2026/TT-BKHCN, mobile subscribers have been required since April 15, 2026 to supplement or verify the registration information associated with their phone numbers. Required information includes a personal identification number, name, date of birth, and facial biometrics. For Viettel customers, My Viettel is an important channel for completing the process remotely. Within the app, users can photograph identity documents, read NFC chips, complete facial recognition, synchronize VNeID information, provide an electronic signature, and confirm the process via OTP. The mandatory nature of real-name verification therefore became the direct cause of the concentrated surge in the app's Q2 downloads.
Over the longer term, the circular's impact may not be limited to telecom operators and their official apps. As phone numbers increasingly serve as important credentials for digital identity and account security, banks, e-wallets, securities platforms, e-commerce services, and social media apps that commonly rely on phone numbers for registration and SMS-based OTP verification may also be indirectly affected. In the short term, the real-name verification policy may trigger a concentrated rise in demand for identity authentication, customer support, and account migration, while also affecting login, payment, and risk-control data for related apps. In the long term, tighter linkage between phone numbers and real identities should help reduce fake SIM cards, fraudulent registrations, account theft, and SMS scams, supporting further improvements in digital payments, digital identity, and anti-fraud services.
Overall, My Viettel's growth reflects not only a temporary shift in demand for a single carrier app, but also Vietnam's accelerating standardization of mobile communications infrastructure and its digital identity system. Although Circular No. 08 applies directly to Vietnam, the policy-driven demand for digital services that it illustrates also offers a useful reference for other Southeast Asian markets.
AI Apps Continue to Penetrate the Market as Qwen Rapidly Acquires Users in Indonesia
During the period, Qwen, Alibaba's generative AI app, rapidly gained traction after entering the Indonesian market in mid-February. Its Q2 downloads rose 821% quarter on quarter to more than 3.62 million. Meanwhile, ChatGPT and Claude by Anthropic, which entered Southeast Asia earlier, saw growth that was more pronounced on the revenue side. ChatGPT topped Southeast Asia's Q2 ranking of fastest-rising non-game apps by revenue, generating estimated revenue of more than US$19.83 million, up over 48.3% quarter on quarter.
The differing download and revenue performance of AI apps shows that Southeast Asia's AI application market is advancing user expansion and monetization in parallel. In terms of competitive strategy, Qwen and ByteDance's Dola more clearly demonstrate the ability of AI products to acquire users at scale. Qwen rapidly accumulated new users through a relatively low barrier to entry and broad Android coverage, while Dola benefited from conversion within ByteDance's product and traffic ecosystem. Overall, both products remain at an early stage of overseas expansion and user accumulation in Southeast Asia. Whether they can convert download growth into stable retention and revenue remains to be seen.
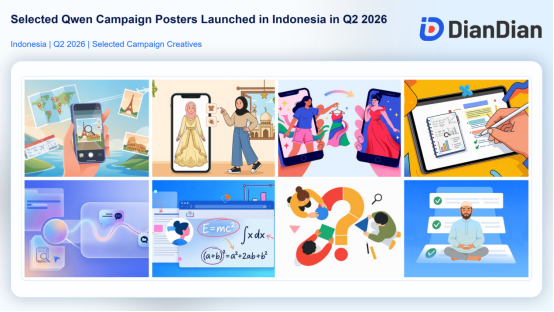
By comparison, revenue growth for ChatGPT and Claude by Anthropic more strongly reflects increasing value extraction and paid conversion from existing users. Rising demand for more capable models, higher usage limits, and premium features is pushing mature products to shift from new-user growth toward increasing value per user. ChatGPT's revenue growth in Q2 was particularly stronger than its download growth, indicating that its commercialization is no longer driven solely by user-base expansion, but increasingly by deeper engagement and improved paid conversion rates.
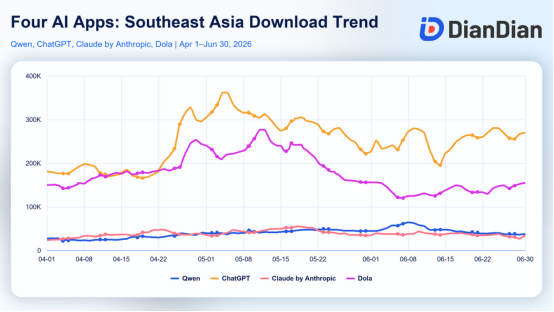
The performance of these four products reflects the continued penetration of AI applications in Southeast Asia. As regional users become more familiar with generative AI, competition will move beyond the pursuit of incremental downloads toward local-language adaptation, broader use-case coverage, user retention, and paid conversion efficiency.