文
A

Downloads Continue to Grow as Adventure and Simulation Revenue Rises Clearly
According to DianDian data, total mobile-game downloads in Southeast Asia maintained steady growth in Q3 2026, rising more than 3.28% quarter over quarter. Revenue declined slightly, down 0.31%. By market, Vietnam was the only market where downloads fell; all other markets grew to varying degrees, with Singapore and Myanmar recording double-digit gains. On the revenue side, the Philippines was the only market with relatively clear growth. Southeast Asian mobile-game downloads continued to grow at a double-digit year-over-year rate, while revenue rose more than 2.1% year over year.
By platform, Google Play continued to contribute the larger share of both downloads and revenue. Its download share exceeded 83%, making it the main user-acquisition platform for Southeast Asian mobile games. Compared with the previous quarter, the App Store’s shares of downloads and revenue both rose slightly. Revenue per download was approximately 3.8 times higher than on Google Play, and the platform’s users continued to demonstrate stronger spending power.
By category, casual, simulation and action ranked highest by downloads, while revenue was concentrated in strategy, casual and role-playing games. Although lightweight categories still dominated downloads, role-playing and sports among mid-tier categories recorded relatively strong growth. Interest in World Cup-related events may have significantly supported user growth in Southeast Asia. On the revenue side, adventure and simulation games grew clearly.
Licensed Characters and a Strategy Experience: Flash Peak Keeps Football Games Hot
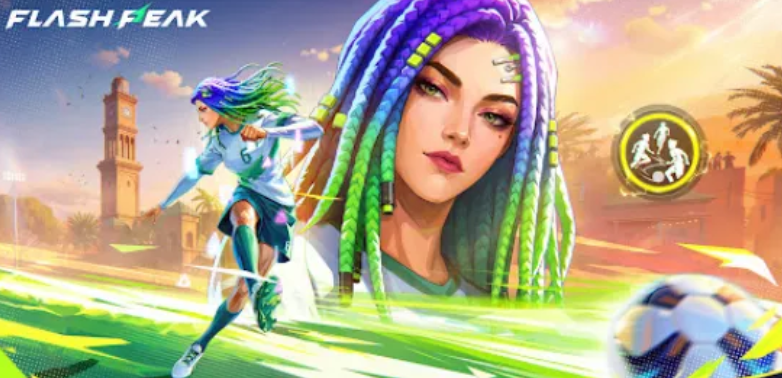
After Total Football VNG attracted significant attention in Q2, the arrival of the World Cup in Q3 brought another standout football release to Southeast Asia. Flash Peak, launched by Moco Studios on Google Play in mid-July, topped the regional mobile-game download growth chart with more than 5.47 million incremental downloads.
Flash Peak compresses a football match into approximately five-minute, four-versus-four real-time games. From a third-person perspective, players control one character and participate through movement, passing, tackling and shooting, while combining different characters’ unique skills. The game simplifies interruptions caused by rules such as offside and fouls, focusing on continuous action and team coordination. For mobile users who want to start a match at any time, the design is easy to learn while preserving the fun of competing with friends in teams.
The product also introduces licensed Free Fire characters, each with distinct skills and roles, and supports custom rooms, friend matches and real-time voice chat. For users familiar with Garena, this character design lowers the learning cost. Football itself is widely popular in Southeast Asia, and the launch broadly coincided with the most closely watched final knockout stages of the World Cup. Tournament interest therefore helped the product secure its first wave of exposure.
Across the full download growth chart, new releases such as Mystery Dumpling, Painty Hide n Seek, Easy Drum and Bracelet Maker were also active, covering puzzles, drawing, music and crafts. This shows that opportunities in Southeast Asia’s lightweight game market are not limited to one mechanic. Flash Peak extends the same path into football competition by simplifying rules and shortening matches, making a relatively demanding format more accessible to a broad audience.
Classic IP and Nostalgia Again Demonstrate Strong Regional Revenue Conversion
If lightweight new releases were the highlight on the download side, familiar classic IPs were central to revenue growth. In Q3, Ragnarok: The New World, published by Gravity, topped Southeast Asia’s mobile-game revenue growth chart with more than $9.1 million in estimated incremental revenue and entered the regional revenue Top 10. CookieRun Classic and CookieRun: Crumble added more than $4.2 million and $1.37 million, respectively. Growth from two classic IP series shows that nostalgia still has strong power to drive spending in Southeast Asia.
Ragnarok: The New World launched in Southeast Asia in mid-July. It adds open-world play, parties, trading and marriage systems to the familiar classic RO universe, while reducing the daily progression burden through offline auto-hunting. Estimated regional monthly revenue rose from approximately $1.79 million in July to $3.86 million in August and remained around $3.46 million in September. Returning users and new-player attention generated by the classic IP ultimately converted into relatively stable in-app purchase revenue.
The CookieRun series takes a more direct nostalgia-driven approach. CookieRun Classic returns to the early side-scrolling runner format, preserving familiar jumping, sliding and jelly collection while extending play through character, pet and treasure collection and league competition. Q3 release CookieRun: Crumble also entered the revenue growth chart, further showing that CookieRun’s IP influence is not concentrated in a single product.
Overall, Ragnarok: The New World and the two CookieRun titles together validate the revenue-conversion power of classic IP and nostalgia in Southeast Asia. Turning nostalgia into long-term revenue, however, still depends on whether products can consistently provide content worth investing in.

Growth Slows on Both Platforms as Thailand’s Revenue Remains Stable
In the non-game app market, total Southeast Asian downloads grew 3.46% quarter over quarter in Q3, while estimated total revenue grew 0.21%, also showing slower momentum. Indonesia remained the region’s largest source of downloads, contributing 34.2%. Singapore, Laos and other mid- and lower-tier markets recorded stronger growth. Thailand contributed more than 28.1% of regional revenue from 11.1% of downloads, maintaining outstanding monetization efficiency and remaining the most important revenue source in Southeast Asia’s non-game app market. With revenue declining in most markets, stable growth in Thailand and Myanmar helped keep regional revenue positive.
By platform, Google Play remained Southeast Asia’s main acquisition platform, contributing 64.9% of non-game app downloads in Q3. The App Store contributed approximately 35% of downloads but more than 55.9% of revenue. Revenue per download was about 2.4 times higher on the App Store than on Google Play, further highlighting the stronger spending power of its users.
By category, entertainment, tools and social communication ranked highest in downloads, while revenue was concentrated in entertainment, photo and video, and social communication. Social communication apps grew clearly in both downloads and revenue in Q3, making the segment one of the quarter’s most active.
Service Migration Drives Rapid Download Growth for Viettel Tammi
During the period, Viettel’s new app Viettel Tammi topped the download growth chart with more than 7.54 million incremental downloads in Q3. In an announcement on September 17, Viettel said it would gradually integrate services from My Viettel into Viettel Tammi and planned to end My Viettel services on October 1. This may have been the most direct reason for the sharp increase in downloads.
Viettel’s traffic redirection to Viettel Tammi did not begin with the September announcement. From late June through July, the platform had already introduced eSIM applications, broadband services and related promotions, gradually taking over communications services previously distributed across other channels. My Viettel had allowed users to check data usage, pay bills and activate 4G and 5G plans, validating demand for the digital delivery of operator services. However, concentrating on communications also limited the app’s use cases and growth space.
Viettel’s migration of My Viettel services to Viettel Tammi therefore looks more like a product-positioning upgrade. The new platform brings together mobile, broadband and television services and also connects to e-signatures, Viettel Post, VTPay, TV360 and partner functions such as ride-hailing and shopping. Users gain one entry point for operations previously spread across multiple apps. Viettel can use its communications user base to drive cross-conversion into payments, video and lifestyle services while reducing the operating costs of maintaining multiple apps in parallel.
The handover from My Viettel’s rapid Q2 growth to Viettel Tammi’s Q3 scaling shows that Viettel is upgrading its operator app from an online service tool into a digital entry point covering more everyday scenarios. Combining local services with communications infrastructure may become a growth path worth watching in Vietnam and across Southeast Asia’s non-game app market.
Short-Drama Apps Diverge Across Downloads and Revenue as Content Competition Deepens
Short dramas remained an important growth direction for Southeast Asia’s non-game apps in Q3. DramaWave ranked second on the download growth chart with more than 5.78 million incremental downloads, exceeding 12.88 million downloads for the quarter and growing more than 81.5% quarter over quarter. On the revenue side, DramaBox ranked fifth among non-game apps with more than $9.62 million in estimated revenue, up more than 9.7% quarter over quarter, and ranked second on the revenue growth chart. Mature products continued to expand, while new releases also found room to enter, with apps such as Halo Reels and MixReels appearing among the quarter’s ranked products.
Download and revenue growth were not fully synchronized. DramaWave’s downloads grew more than 80%, but revenue rose only 3.6% quarter over quarter, suggesting that large-scale acquisition had not yet fully converted into paid revenue. By contrast, StoryReel’s revenue grew 452.6% quarter over quarter, while AI animation-drama app VibeShort grew revenue 49.3%. Products focused on narrower content and new formats achieved clearer breakthroughs on the revenue side.
The rankings show that Southeast Asia’s short-drama market continued to heat up in Q3, but its growth model is changing. Leading platforms can still rapidly expand downloads through acquisition and continuous releases. Apps such as StoryReel and VibeShort, with more focused content positioning and more distinctive formats, performed particularly well on revenue. For short-drama platforms in Southeast Asia, revenue growth no longer depends only on user scale. Capturing market topics in time, keeping up with trends and creating differentiated content around niche themes are becoming equally important.